
What if the RRSP money that brings your down payment within reach also creates a repayment commitment you need to plan for? If you’re buying in BC, the Home Buyers’ Plan can let eligible buyers withdraw up to C$60,000 per person from their RRSP, but it isn’t extra cash with no strings attached. This RRSP home buyers plan BC guide explains how to weigh a withdrawal against your savings, mortgage plans, and purchase timeline.
You’ll learn what to check about first-time buyer eligibility, qualifying homes, RRSP contribution timing, and repayment rules, including when repayments begin and what happens if you miss one. We’ll also consider how the HBP may fit alongside other first-time buyer programs and closing funds. Before acting, confirm current requirements with the CRA and a qualified tax or financial professional. Use the questions in this guide to build a purchase plan with fewer surprises.
Key Takeaways
- Check whether your purchase and circumstances meet federal HBP rules before requesting an RRSP withdrawal.
- Confirm current CRA requirements, deadlines, forms, and tax reporting details before accessing RRSP funds, and keep records throughout the process.
- Compare the HBP with the FHSA to understand how their different access and repayment rules may affect your plan.
- Map your savings and purchase timeline against your deposit, closing funds, and mortgage planning before deciding how much to withdraw.
What the RRSP Home Buyers’ Plan means for BC home buyers
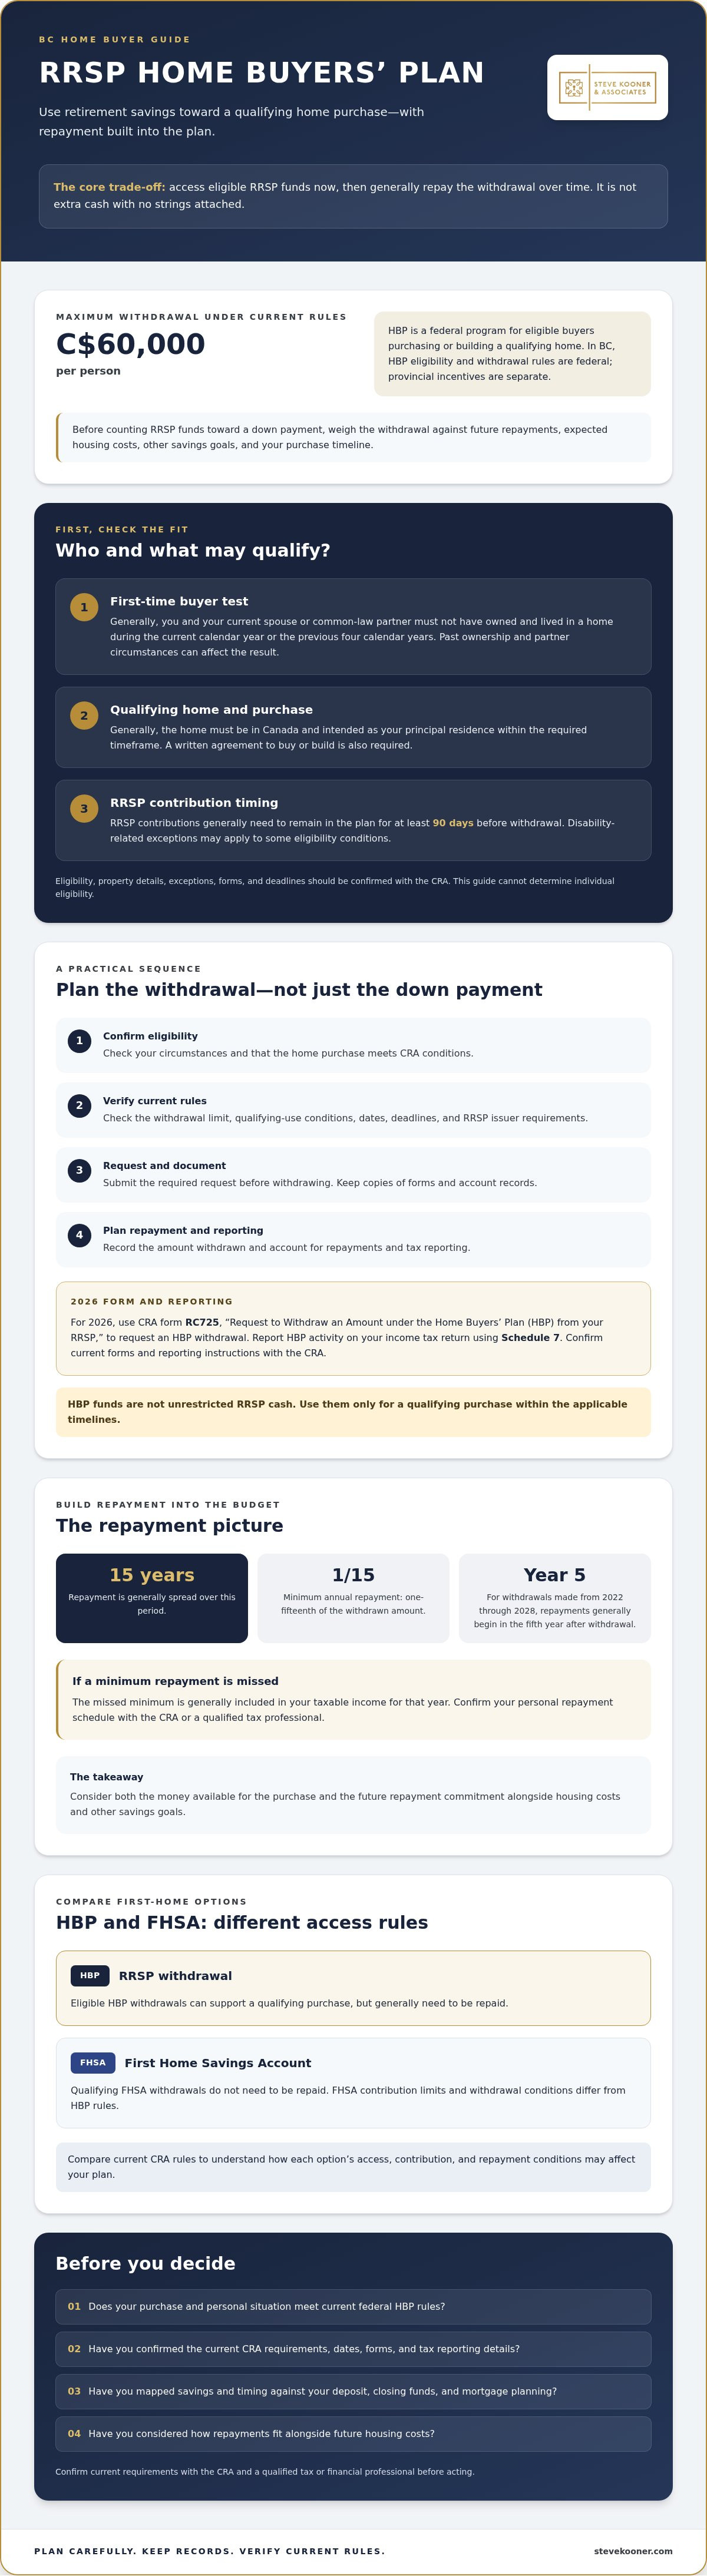
The Home Buyers’ Plan (HBP) is a federal program that lets eligible buyers withdraw money from their RRSP to purchase or build a qualifying home, subject to CRA rules and repayment requirements. For BC residents, HBP eligibility and withdrawal rules are federal; provincial incentives and other federal programs are separate. The key trade-off is that you can access retirement savings now, but generally need to repay the withdrawal over 15 years. For withdrawals made from 2022 through 2028, repayments generally begin in the fifth year after the withdrawal. Check current CRA guidance before relying on these timelines. For a brief background overview, see the Home Buyers’ Plan (HBP).
Before counting RRSP funds toward your down payment, compare the amount you might withdraw with the repayments you’ll need to plan for, your expected housing costs, and your other savings goals.
For another perspective on preparing to buy your first home in BC, watch this buyer-focused video:
Who may qualify, and what counts as a qualifying home?
CRA rules generally require you to meet its first-time buyer test. This usually means you, and your current spouse or common-law partner, didn’t own and live in a home during the current calendar year or the previous four calendar years. Past ownership and partner circumstances can affect the result, so confirm how the test applies to you with the CRA.
The home must meet the CRA’s qualifying-home conditions. Generally, it must be in Canada and intended as your principal residence within the required timeframe. You also need a written agreement to buy or build, and RRSP contributions generally need to remain in the plan for at least 90 days before withdrawal. Disability-related exceptions may apply to some eligibility conditions. Verify the current rules, qualifying property details, forms, and deadlines with the CRA before acting. This guide can’t determine your eligibility.
How to use the RRSP Home Buyers’ Plan without overlooking repayment
Plan the withdrawal as a sequence, not a last-minute source of cash. First, check your eligibility. Then confirm the current limit, qualifying-use conditions, dates, and forms against the official Home Buyers' Plan rules. The maximum withdrawal is C$60,000 per person under current rules.
- Confirm your eligibility and that the home purchase meets CRA conditions.
- Check the current withdrawal limit, deadlines, and RRSP issuer requirements.
- Submit the required request before withdrawing, then keep copies of forms and account records.
- Record the amount withdrawn and plan for repayments and tax reporting.
For 2026, use CRA form RC725, “Request to Withdraw an Amount under the Home Buyers’ Plan (HBP) from your RRSP,” to request an HBP withdrawal, and report HBP activity on your income tax return using Schedule 7. Confirm the current forms and reporting instructions with the CRA before submitting. HBP funds aren’t unrestricted RRSP cash. Use them only for a qualifying purchase within the applicable timelines.
What repayment means for your future budget
Repayment is generally spread over 15 years, with a minimum annual repayment of one-fifteenth of the withdrawn amount. For withdrawals made from 2022 through 2028, repayments generally start in the fifth year after the withdrawal. A missed minimum is generally included in your taxable income for that year. Confirm your personal repayment schedule with the CRA or a qualified tax professional.
Use a mortgage payment calculator to explore housing-budget scenarios. It doesn’t calculate HBP repayments or tax. As you compare homes and plan an offer, keep the purchase timeline and available funds in view. A local real estate team can help with property searches and offer planning.
How the HBP fits into a BC home purchase and other first-home options
The HBP is one possible source of purchase funds, not a complete down payment strategy. Compare it with a First Home Savings Account (FHSA): both have first-time buyer rules, but HBP withdrawals generally need to be repaid, while qualifying FHSA withdrawals don’t. FHSA contribution limits and withdrawal conditions differ, so check the current CRA rules before deciding how the accounts fit together. For the application steps, review the CRA’s guide to how to participate in the HBP. For wider BC program context, see First Time Home Buyer BC Programs: The 2026 Fraser Valley Guide.
Build your funds plan around the expected purchase timeline. Separate money for the deposit from funds reserved for closing costs, then consider how the mortgage payment and future HBP repayments fit your budget. The RRSP home buyers plan BC guide is most useful when you weigh a potential withdrawal against these other needs, rather than treating the maximum as a target.
Questions to resolve before making an offer
- Does your expected purchase date and the specific home meet CRA conditions?
- Can your RRSP issuer process the withdrawal in time, and have you confirmed the forms and deadlines?
- How will the deposit, closing funds, mortgage plan, and future repayments work together?
Confirm HBP and FHSA eligibility, withdrawal timing, and tax treatment with the CRA or a qualified adviser. Coordinate the overall funds plan with a mortgage professional. A mortgage payment calculator can help you explore payment scenarios, while local first-time buyer guidance can support your property search and offer planning. To discuss the real estate steps, you can contact the team.
Plan your next move with confidence
The HBP can help bring a BC home purchase within reach, but it works best as part of a broader plan. Before withdrawing, confirm your eligibility, qualifying purchase details, deadlines, and forms with the CRA. Then consider how repayment and your other savings fit your budget. The main takeaway from this RRSP home buyers plan BC guide is to coordinate your funds and timing before making an offer, and to ask a qualified tax or financial professional about personal tax questions.
From Langley, the Township of Langley, and Surrey to Abbotsford, Chilliwack, Mission, Hope, Kent, Agassiz, Harrison Hot Springs, North Delta, Maple Ridge, and Pitt Meadows, Steve Kooner & Associates supports buyers with property searches, offers, negotiations, and transaction coordination. The team can help you work through the real estate steps while you confirm HBP decisions with the right advisers.
With a clear plan and trusted support, you can move toward your first home one confident step at a time.
Frequently Asked Questions
How much can you withdraw from your RRSP under the Home Buyers’ Plan in 2026?
In 2026, an eligible person can withdraw up to C$60,000 from their RRSP under the HBP. If both qualify, two buyers may each withdraw up to the individual limit. These federal rules apply in Langley, Township of Langley, Abbotsford, Chilliwack, Mission, Hope, Kent, Agassiz, Harrison Hot Springs, Surrey, North Delta, Maple Ridge, and Pitt Meadows. Confirm current CRA requirements before requesting funds.
Who is eligible for the RRSP Home Buyers’ Plan in BC?
Generally, you must meet the CRA’s first-time buyer test, have a written agreement to buy or build a qualifying home, and meet the program’s other conditions. The test considers whether you or your current spouse or common-law partner owned and lived in a home during the current year or previous four calendar years. RRSP funds generally need to be held for at least 90 days. Check your circumstances with the CRA.
Do you have to repay an RRSP withdrawal under the Home Buyers’ Plan?
Yes. HBP withdrawals are generally repaid to your RRSP over 15 years, with annual minimum repayments. For withdrawals made from 2022 through 2028, repayments generally begin in the fifth year after the withdrawal. If you don’t make the required minimum repayment, the missed amount is generally included in your taxable income for that year. Confirm your personal schedule and reporting obligations with the CRA or a qualified tax professional.
Can you use the HBP and an FHSA for the same home purchase?
Yes, you may be able to use both for the same qualifying home purchase if you meet each program’s requirements. A qualifying FHSA withdrawal doesn’t need to be repaid, but HBP withdrawals do. The programs have separate eligibility, withdrawal, and reporting rules, so confirm your plan with the CRA or a qualified adviser. Use this RRSP home buyers plan BC guide as a starting checklist, not an eligibility decision.
Disclaimer
"Not intended to solicit buyers or sellers that are under current agency agreement" "Each RE/MAX office is independently owned and operated"


